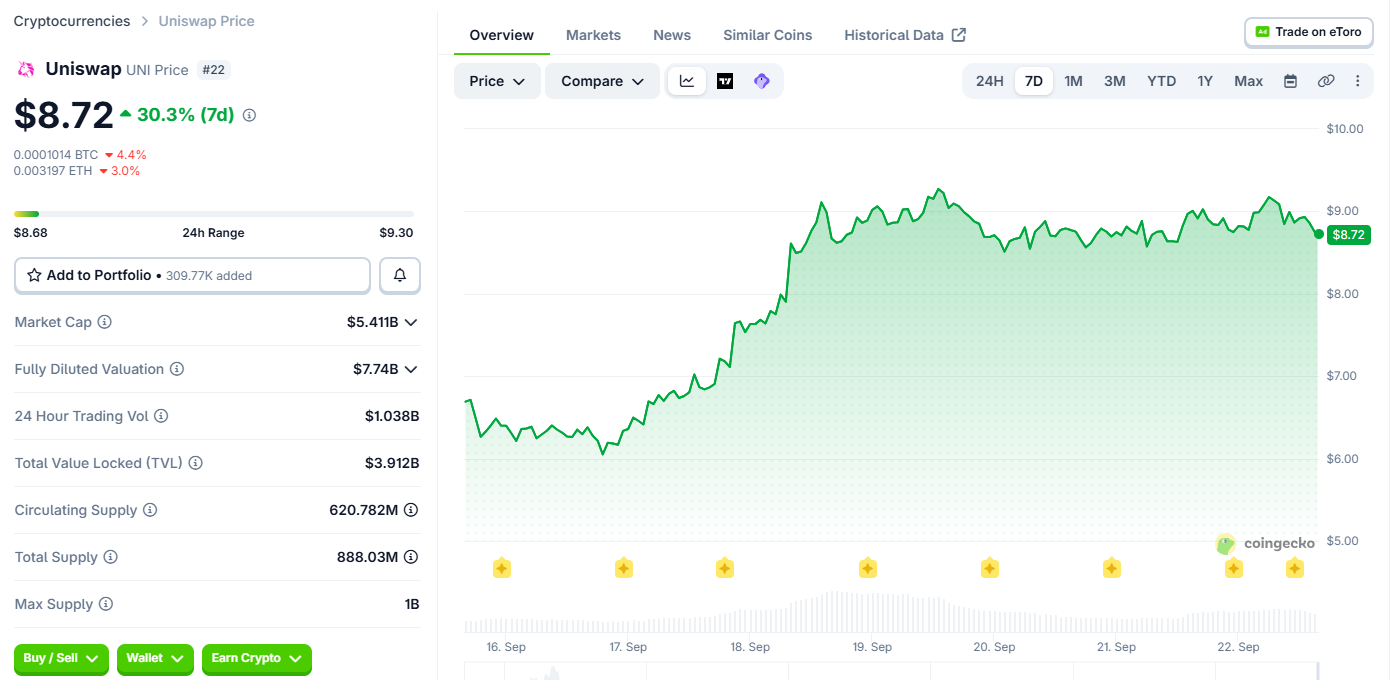
"Tokenization is coming to America," declared Robinhood Chief Executive Vlad Tenev after the United States Securities and Exchange Commission announced its landmark Innovation Exemption. The regulatory development immediately resonated across the broader digital asset economy, prompting a swift and positive reaction from market participants and investors alike. In the days following the announcement, bellwether cryptocurrencies Bitcoin (BTC) and Ethereum (ETH) surged by more than 10%. Meanwhile, decentralized finance protocols experienced even more dramatic inflows, most notably Uniswap’s UNI token, which gained over 30% as traders began eyeing the protocol as a potential prime infrastructure layer for onchain stock trading.
While the Securities and Exchange Commission has indeed greenlit a pathway for tokenized stocks in America, a closer examination of the policy reveals that the vast majority of existing stock tokens currently circulating in the market fall outside the boundaries of the new regulatory framework.
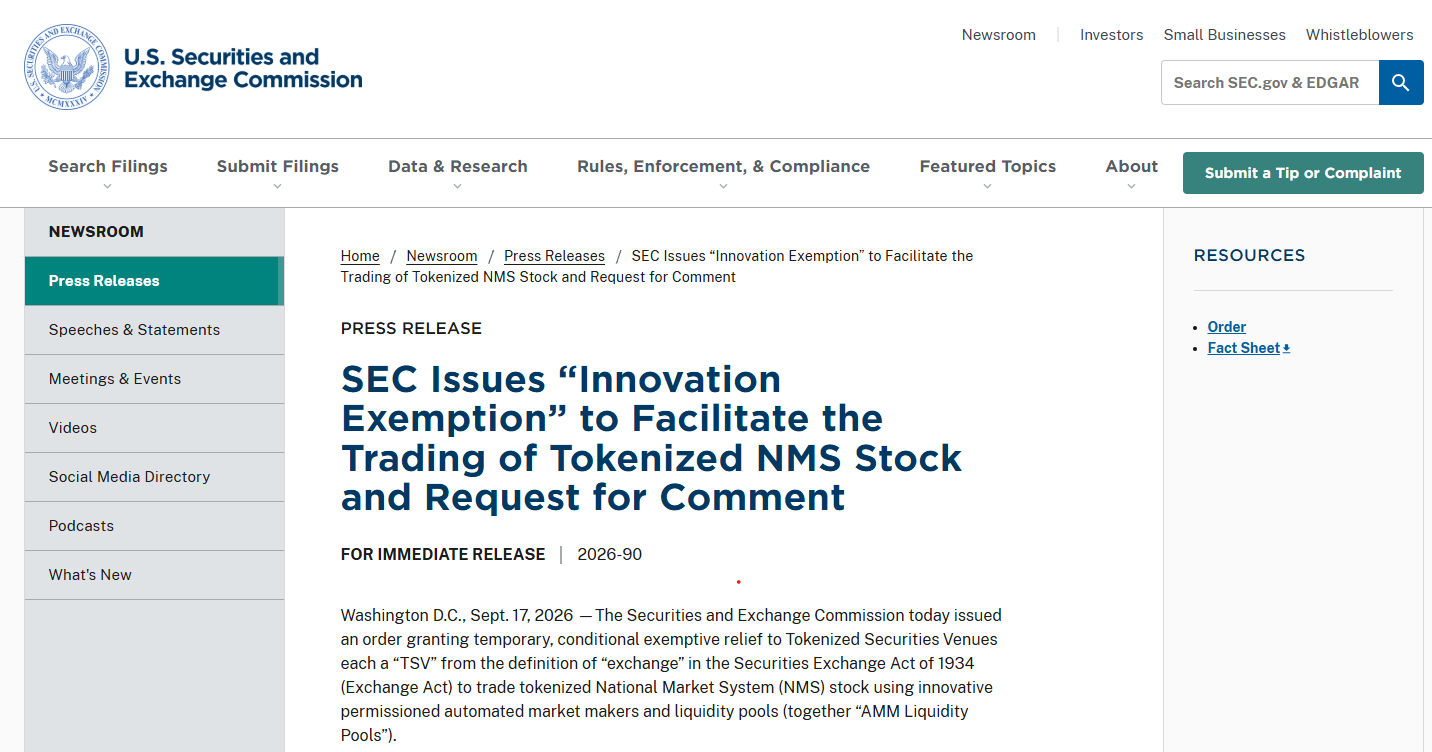
The commission’s new five-year Innovation Exemption creates a specific legal pathway for qualified venues to trade tokenized National Market System (NMS) stocks onchain without needing to register as traditional securities exchanges. Furthermore, the ruling permits third parties to tokenize equities, but this activity is strictly confined to a narrow and demanding set of operational conditions.
Under the new regulatory parameters, tokenized assets must guarantee that holders possess the exact same "rights and privileges" as the underlying traditional shares. Additionally, trading venues are mandated to strictly permission users and liquidity pools to ensure ongoing compliance with federal oversight requirements.
The SEC’s Tokenization Lane is Narrow
Not all tokenized stocks are created equal in the eyes of regulators. Within the digital asset ecosystem, a token can easily mimic the visual presentation of a share and closely track its price movement without ever granting the fundamental corporate governance rights associated with traditional equity ownership. Under the SEC’s newly established rules, any instrument that achieves price tracking without delivering true underlying shareholder rights is officially classified as a synthetic stock, rendering it completely non-compliant with the exemption.
This strict definition means that some of the industry’s most prominent players may already possess a valuable head start, while others will be forced into an aggressive scramble to pivot their technology. As Peter Curley, head of global regulatory affairs at Ondo Finance, noted in a discussion with industry reporters, regulatory pragmatism is taking center stage: "Not everything we do will fit, and that’s fine. What matters is that the SEC acted instead of waiting on Congress to finish the job."
The SEC’s Sept. 17 order grants specific trading venues temporary relief from traditional exchange registration requirements when they facilitate the trading of tokenized NMS stocks through permissioned Automated Market Maker (AMM) liquidity pools. In essence, the regulatory agency has deliberately carved out a dedicated lane for onchain stock trading, but it is a remarkably specific pathway where the structural design of the token itself carries just as much legal weight as the operational mechanics of the trading venue.
To qualify under the exemption, a tokenized stock must ensure that holders receive identical dividends, voting rights, and corporate action benefits as the underlying physical security. While third parties retain the ability to tokenize a stock without maintaining a direct corporate affiliation with the original issuer, the underlying stock issuer is granted the explicit right to veto or reject the token before it can officially be offered for trading.
This structural requirement effectively rules out synthetic exposure models. That outcome presents an immediate challenge for existing products such as Robinhood’s Stock Tokens and Kraken’s xStocks in their current architectural iterations.
During the announcement, SEC Commissioner Hester Peirce emphasized that the temporary exemption is purposefully tailored to accommodate one particular operational model rather than every conceivable method of trading tokenized securities. Nevertheless, she noted that the commission remains open to evaluating alternative models outside of the specific tokenized securities venue structure as the market continues to mature.
The Products Closest to the SEC’s Model
Examining the current landscape reveals that certain existing industry offerings are already operating remarkably close to the SEC’s prescribed model. Coinbase’s tokenized stock initiatives, for instance, sit firmly within the ballpark of compliance.
On Sept. 14, Coinbase Chief Executive Brian Armstrong stated that his company had successfully "set the standard" with its tokenized stock offerings. He emphasized that these products are neither synthetic instruments nor debt obligations, but rather "real fully-backed securities, redeemable for the underlying shares, with dividends integrated," alongside voting rights capabilities that are "coming soon."
However, a technical mismatch remains. Coinbase’s current tokenized stock offerings are primarily tailored for international customers outside the United States, and the exchange’s underlying core infrastructure is built around a traditional central limit order book rather than the permissioned AMM liquidity pools specified by the SEC exemption. Nevertheless, because Coinbase operates the prominent Base blockchain network, the firm maintains significant architectural flexibility to adapt its systems moving forward.
Similarly, Ondo Finance launched tokenized United States securities in June, utilizing an architecture where the underlying physical shares are held in traditional institutional custody, while the digital token directly represents the investor’s legal entitlement onchain.
Furthermore, Ondo expanded its regulatory footprint by acquiring Oasis Pro, an entity that includes an SEC-registered broker-dealer, an Alternative Trading System, and a transfer agent. This strategic acquisition provides the firm with comprehensive compliance infrastructure bridging both the traditional financial markets and the onchain ecosystem.
Curley observed that the SEC’s exemption heavily favors "exactly the model we’ve already proven out: custodial, entitlement-based, with real shareholder rights and corporate actions passing through to the holder." However, he maintained a cautious outlook, adding, "We’re not assuming anything clears automatically."
Both Coinbase and Ondo currently possess critical components of the technological and regulatory infrastructure that the SEC appears to desire. While neither company can simply assume that its existing operational setup qualifies without some necessary adjustments, they may ultimately face a significantly shorter road to full compliance than many of their competitors.
Uniswap’s Permissioned Pools Could Open the Door
Because the SEC’s exemption is explicitly designed around permissioned AMM liquidity pools, the regulatory shift appears to present a major strategic opportunity for decentralized finance protocols like Uniswap.
The Uniswap protocol introduced Permissioned Pools for its v4 iteration in July, a development designed to allow regulated financial assets to trade seamlessly through AMMs while enforcing compliance checks directly onchain. While this technical capability does not automatically transform Uniswap itself into a recognized tokenized securities venue, its v4 infrastructure can easily be utilized by market operators who are building compliant platforms. These Permissioned Pools enable asset issuers to exercise precise control over who is permitted to trade or provide liquidity, aligning directly with the core requirements outlined by the SEC.
Permissioned access mechanisms inherently require robust Know Your Customer verification procedures, comprehensive record-keeping frameworks, public transaction notices, and total operational transparency. If this decentralized technological infrastructure can be successfully bridged with the stringent shareholder rights and regulatory compliance mechanisms mandated for US securities trading, Uniswap possesses a flexible framework that could be readily adapted to fit the SEC’s preferred operational model.
Robinhood Has the Users, But Not the Right Product
Robinhood already boasts approximately 200 distinct stock tokens actively trading on its proprietary Robinhood Chain. Chief Executive Vlad Tenev has previously described the network’s offerings as being backed on a one-to-one basis and fully composable within the broader decentralized finance ecosystem.
However, Jaewon Kim, head of research at Four Pillars, pointed out that the SEC’s exclusion of synthetic exposure effectively disqualifies popular products like Robinhood’s Stock Tokens and Kraken’s xStocks from utilizing the exemption.
Robinhood’s current Stock Tokens function as tokenized debt securities issued by Robinhood Assets (Jersey) Limited. Consequently, they provide investors with economic exposure to the underlying equities without granting them direct legal or beneficial shareholder rights. Moreover, these instruments are not registered under United States securities laws and remain entirely unavailable to US persons.
Despite the fact that Robinhood’s existing product lineup does not currently conform to the SEC’s rigid compliance rules, the company’s massive retail user base and advanced blockchain infrastructure could afford it a substantial competitive advantage if management successfully pivots the product model to meet the new federal requirements.
Similarly, Kraken’s xStocks are fully backed by underlying equities, yet they likewise fail to provide holders with the identical legal rights associated with conventional shares. As market analysts emphasize, simply being backed by physical shares is insufficient to qualify for this particular regulatory exemption.
Bryan Choe, head of research and operations at RWA.xyz, a prominent market intelligence platform dedicated to tokenized real-world assets, noted that the vast majority of existing tokenized equity products are currently sponsored by third parties. However, he anticipates a profound structural shift over the coming year.
"We expect most of the products to shift to issuer-sponsored models," Choe explained, emphasizing that the new exemption effectively "aligns the token issuers with the stock issuers," which could eventually restore a healthy operational balance across different market issuance strategies.
Five Years to Prove Tokenized Stocks Are Actually Better
The Securities and Exchange Commission has explicitly described the new regulatory framework as a temporary exemption. SEC Chairman Paul Atkins noted that this five-year observation period will provide the broader financial market with adequate time to "develop" and innovate while the commission evaluates potential future rulemaking initiatives.
Beyond the race to determine which specific financial institution or technology firm will successfully deploy the first fully compliant trading venue, the ultimate test for the industry will be whether tokenized equities can achieve widespread commercial adoption.
As Curley noted, investors must ultimately be provided with a financial vehicle that is demonstrably "faster, cheaper, or more useful than a conventional brokerage position." Already, industry analysts have raised valid questions regarding whether fragmented liquidity across various tokenized stock platforms will be capable of consistently delivering competitive asset pricing and a seamless user experience.
The new regulatory exemption carries the theoretical potential to unlock continuous 24/7 trading, granular fractional ownership, instantaneous settlement speeds, onchain composability, and preserved shareholder rights. Ultimately, however, these sophisticated technological advantages will only matter if mainstream investors find genuine utility and value in the resulting financial products.